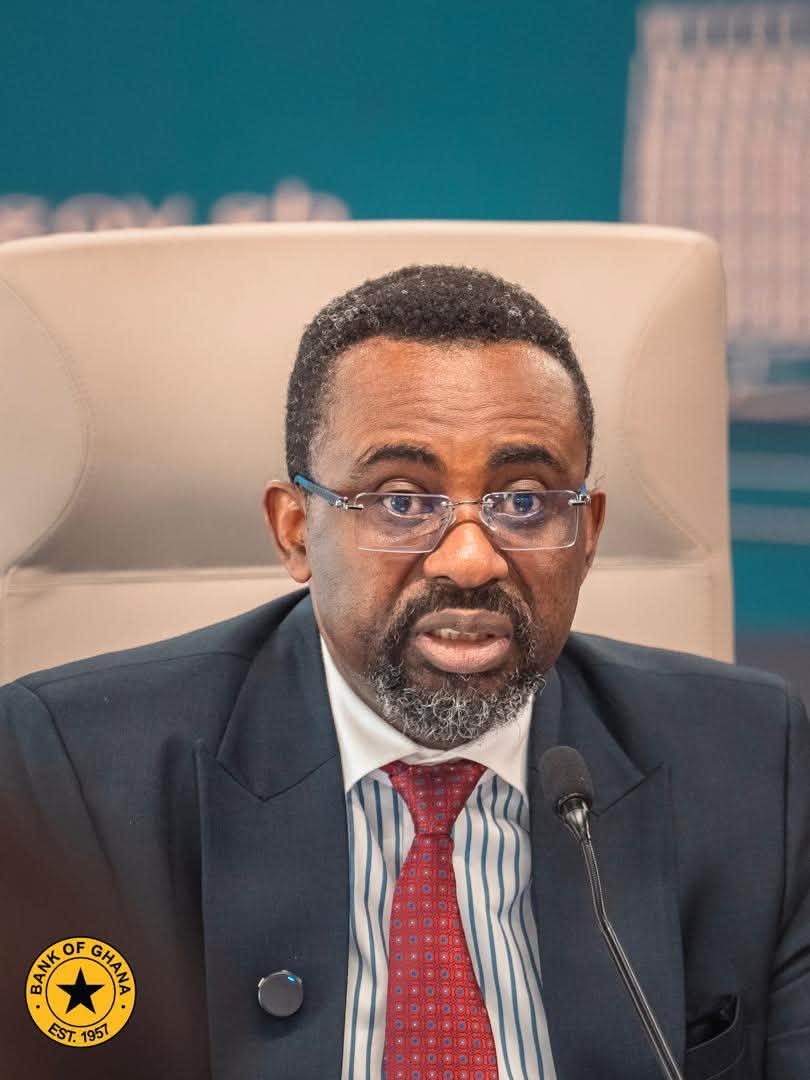
Governor of the Bank of Ghana, Dr Johnson Asiama, says the rapid expansion in private sector credit does not currently pose a threat to liquidity management, arguing that the country still has room to accommodate further lending growth.
His comments follow a significant increase in private sector credit growth, which rose to 37.2 per cent, compared with 13.9 per cent during the corresponding period.
In real terms, credit to the private sector expanded by 30 per cent, up from 5.4 per cent, reflecting improved lending conditions and increased demand for credit.
Speaking at a media engagement after the 133rd meeting of the Monetary Policy Committee on Wednesday, November 18, Dr Asiama said the Bank’s assessment showed that the growth in lending remained within manageable levels.

He explained that the credit-to-GDP gap indicated that the economy had sufficient room to accommodate additional private sector lending without creating immediate risks to liquidity management.
“For now, it’s under control,” he said.
Dr Asiama noted that private sector credit as a proportion of Ghana’s Gross Domestic Product remained relatively low at 8.8 per cent, compared with levels in other African economies.
He cited Kenya and South Africa as examples of countries with significantly higher private sector credit-to-GDP ratios.
According to him, Ghana’s relatively low credit penetration means that the current expansion in lending should be considered against the country’s historical position and the need to deepen financial intermediation.
The governor’s comments come amid improving lending conditions in the banking sector.
The average lending rate declined to 15.8 per cent from 22.2 per cent over the comparative period, while financial soundness indicators also improved.
The banking sector’s capital adequacy ratio increased to 18.5 per cent in October 2026, from 17.9 per cent a year earlier.
The non-performing loans ratio also declined to 13.1 per cent, compared with 19.5 per cent over the same period in 2025.
Dr Asiama’s position suggests that the central bank is monitoring the rapid expansion in credit but does not consider the current pace sufficient reason to restrict lending at this stage.