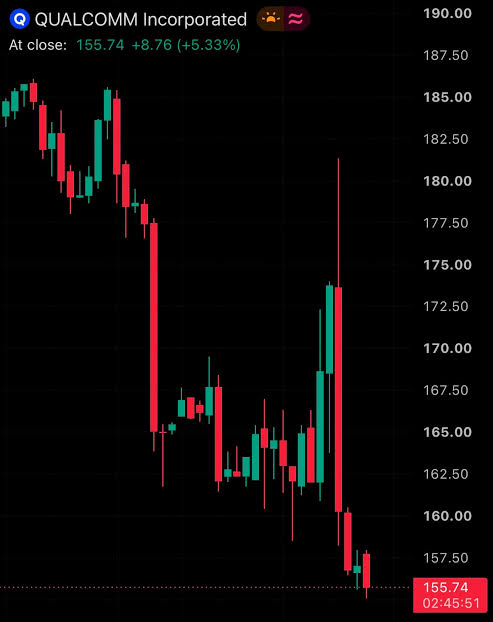
Qualcomm shares fell more than 10 per cent at Thursday’s market open after the chipmaker reported weaker-than-expected handset revenue and warned of rising semiconductor manufacturing costs, raising concerns about its profit margins despite beating quarterly earnings and revenue estimates.
The company reported fourth-quarter adjusted earnings of $2.17 per share, slightly above analysts’ consensus estimate of $2.16. Adjusted revenue reached $10.44 billion, exceeding the expected $10.12 billion.
However, handset revenue fell 26 per cent year on year to $5.14 billion, missing analysts’ estimate of $5.25 billion. Total revenue also declined 7 per cent from $11.27 billion recorded a year earlier.
Qualcomm’s gross margin contracted to 52.4 per cent, below the market expectation of 53.2 per cent, as rising manufacturing costs continued to weigh on profitability.

The company said the semiconductor industry was experiencing widespread cost increases across wafer fabrication, assembly, testing, advanced packaging, memory and other materials. It expects the full benefits of its pricing adjustments to materialise in the second half of fiscal 2027.
For the first quarter, Qualcomm forecast revenue between $10.4 billion and $11.2 billion, with the midpoint of $10.8 billion exceeding analysts’ consensus estimate of $10.55 billion.
However, its adjusted earnings guidance of $2.15 to $2.35 per share placed the midpoint at $2.25, below the analysts’ estimate of $2.32.
Analysts at Goldman Sachs said investors would seek clearer evidence of the scale and timing of Qualcomm’s data centre business expansion through fiscal 2027, particularly amid near-term weakness in the smartphone market.
“Although we believe investor positioning was relatively balanced heading into the quarter, we think investors will want to see more evidence of the magnitude and timing of the Datacenter ramp through FY27 – especially in light of near-term smartphone weakness,” the analysts said in a post-earnings note.
They added that investors would also want to see stronger evidence of gross margin stabilisation before becoming more positive about the stock.
Raymond James analysts expressed similar concerns, pointing to elevated manufacturing costs and the potential impact of data centre custom silicon on margins.
“Elevated manufacturing costs continue to pressure margins, with expected pricing benefits largely offset by Data Center custom silicon dilution,” they wrote.
The analysts said the investment debate had shifted towards the execution of Qualcomm’s data centre strategy, with investors seeking further evidence of customer expansion and margin recovery.
Despite the weakness in handset revenue, Qualcomm recorded strong growth in its automotive business, where revenue surged 89 per cent year on year to $1.99 billion. The figure exceeded analysts’ estimate of $1.69 billion and marked the segment’s first quarter approaching $2 billion in revenue.
Internet of Things (IoT) revenue increased 4 per cent to $1.89 billion, also beating market expectations.
The company’s QCT semiconductor business generated $9.02 billion in revenue, down 8 per cent year on year but above the $8.8 billion consensus estimate.
Revenue from its QTL licensing business declined 7 per cent to $1.30 billion, slightly exceeding analysts’ forecast of $1.29 billion.
Qualcomm President and Chief Executive Cristiano Amon said the company delivered fourth-quarter non-GAAP revenue at the upper end of its guidance, supported by growth in its automotive and IoT businesses.
“We are pleased to deliver fourth-quarter non-GAAP revenues at the high end of our guidance, along with 36% year-over-year growth in combined QCT Automotive and IoT revenues,” Amon said.
He added that fiscal 2027 would mark the beginning of an increase in revenue from businesses outside its traditional handset market, including the expansion of its data centre operations.
“Fiscal 2027 marks the start of our non-handset revenue inflection, including the ramp of our Data Center business,” he said.
For the full 2026 fiscal year, Qualcomm’s adjusted revenue declined 2 per cent to $43.24 billion, while adjusted earnings per share fell 12 per cent to $10.54.